Molly Haylett 0:00
The two biggest things often are the house, the marital home, and pensions, which can be completely different depending on exactly what somebody's got.
Kate Daly 0:12
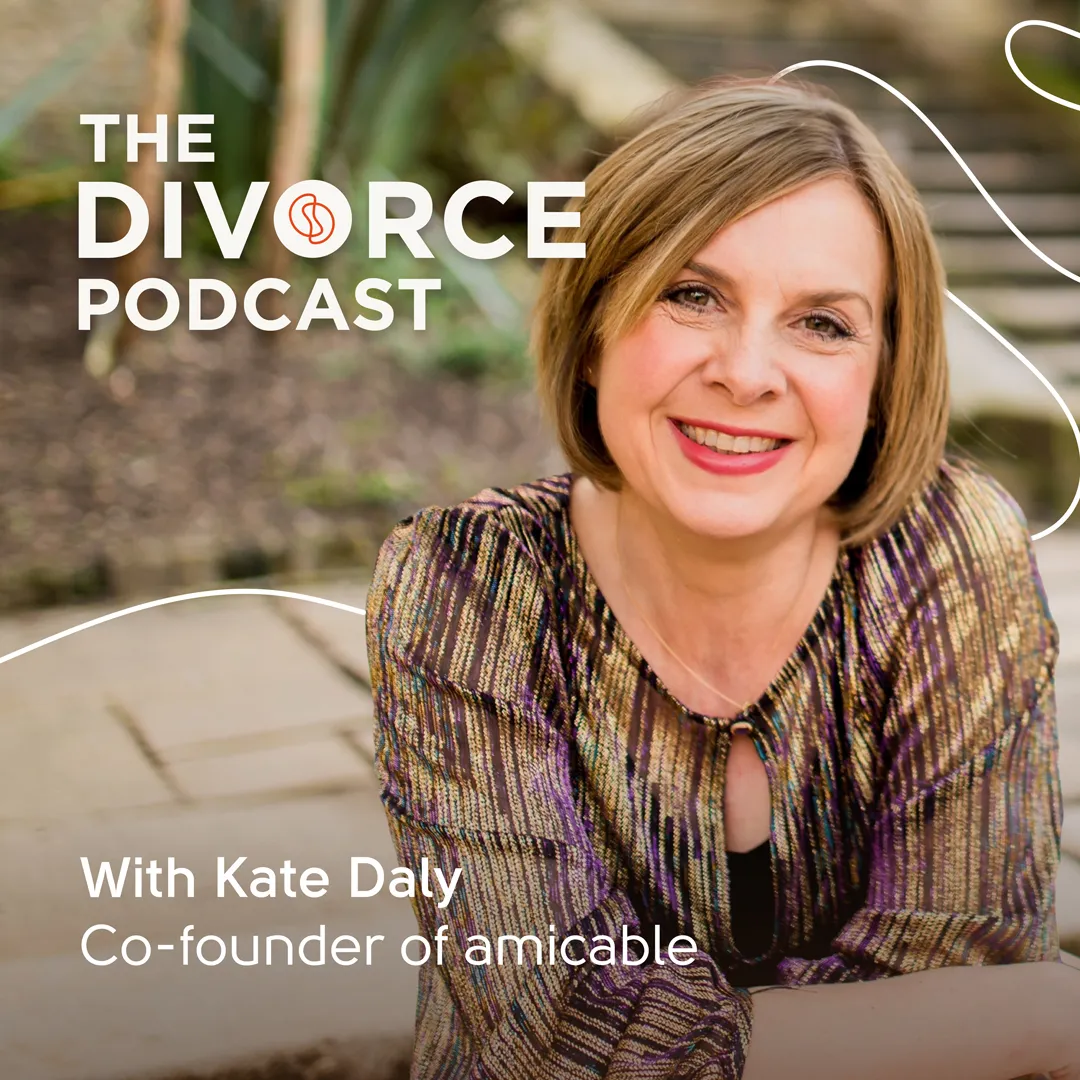
Welcome to the Divorce Podcast, where we explore relationship separation and parenting apart. If your relationship has ended or someone close to you is going through it, this podcast is for you. I'm Kate Daly, a relationship counsellor, divorce expert, and co-founder of amicable, the legal service helping couples navigate relationship change. Each episode looks at separation from a different angle, emotional, legal, or social, and with experts and special guests who share their own stories and tips to help people separate in a kinder, better way. This week I'm delighted to be welcoming back Molly Hailett, Chartered Financial Planner at Octopus Money, for part two of our three-part series on financial planning through divorce. This time we're looking at the middle part of the process, the practical money decisions that come up while things are still being worked through. If you missed part one, then go back and catch Molly's tips for getting ahead financially at the very start of a divorce. And stay tuned for part three, where we'll cover your finances once the divorce is finalised. This episode and our mini-series with Molly is created in partnership with Octopus Money. We discuss general information only and it doesn't constitute regulated financial advice. The tips we discuss are not personalized recommendations. So please do get in touch with an authorised advisor who knows your personal situation before making any financial decisions. Welcome back, Molly. Thank you for having me. Oh, it's lovely to see you again. Thank you for joining us. Now we talked about the beginning part of the process last time. This time it's all about the middle divorce part. So when you're right in the thick of it and you're looking at splitting money, property, all of the rest of it, what financial decisions tend to come up in this phase of the process, would you say?
Molly Haylett 2:10
Yeah, great question. And you're right, you're right. We say you're right in the thick of it. So it's more the mechanics at this point, and actually, right, what do you have and how do we split it, but also how do we know exactly what we've got? I mean, the two biggest things often are the house, the marital home, and pensions, which can be completely different depending on exactly what somebody's got. So with the house, it's normally the first thing is okay, well, how do we get it reliably valued? For which there are a couple of options. So you can go down the kind of conveyancing route, a little bit more expensive, but for most people, they tend to get covered with two or three estate agents around and use a sort of relatively uh middle valuation from there. But then it's also okay, well, the mechanics again of how do you split the house? So are you going to sell and split? So sell the house and kind of split the proceeds, or you're going to keep the house and sell it in the future. Sometimes that's done for so the kids can stay where they are. But the house is generally the largest asset for most people. I find it's their primary concern.
Kate Daly 3:10
And I guess most people have to do something with the house, don't they? So you're either transferring it to your partner for which you'll still need a valuation. I often think that's quite an interesting one because often there's a tension then, isn't there, when you're getting the house valued. For one of you, it's going to be much better to get a low valuation, and for the other one, it's going to be better to get the high valuation. So your point about getting three valuations from a solicitor and then kind of choosing the median point is a really good way of, you know, like you say, most people actually sort it out that way. So are you selling or are you transferring? And the point I think as well about if you're selling is remembering to put the selling fees in because when we're talking about splitting things from a legal perspective, we're always working on net values. So again, super important. So we're looking at net salaries, we're looking at the net proceeds of sales. So that means the sale, once you've taken off state agent fees, solicitor fees. And then when we're looking at affordability, we're also looking at things like mortgage capacities as well. So if you are, it's all very well to say we're gonna split the house 50-50 and we're each gonna go off with our 50%. But again, that can be deeply unfair if one of you's got a huge mortgage capacity and the other one, perhaps they've stayed at home to raise a family, doesn't have that mortgage capacity. So working in what mortgage capacity people have, I think is a really key one at this mid-process as well. And really getting in touch with mortgage broker, somebody who can tell you what your capacity is, because it's not just about what you can afford to borrow, it's how long you've got to pay it back. It's whether or not it's affordable on a month-to-month basis as well.
Molly Haylett 4:57
Yeah, absolutely. Is this really important? But again, it's probably the one of the first things that comes up is and also where do you want to live and what are the property requirements for property in that area? Is in how much will I need to spend in order to stay kind of close to the schools or you know, whatever it might be that's keeping you in that particular area. So, yeah, more how speaking to somebody that they can help you understand your mortgage borrowing capacity, really, really important starting point there as well, alongside the decision around okay, actually, what are we going to do with the house?
Kate Daly 5:28
Because you're part of Octopus Money, aren't you? And you have mortgage people as part of your team, don't you? So if people are listening and they want some help, they can reach out to you for some financial help and support, but also you can put them in touch with your team who do mortgages too.
Molly Haylett 5:45
Yeah, absolutely. Yeah, we have a lovely team that deals mortgages, and it's something that comes up an awful lot, is actually initially, what can I borrow? I don't need a mortgage today, but what can I borrow when I do? And it's very, very useful, particularly in coming into these discussions, feeling informed. Um, exactly like you've said, it's all well and good taking a percentage split that seems fair. But then if you can't have more borrowing or you're um at a point where maybe you're nearly retiring and therefore your your time to borrow is much less than somebody that's you know maybe got 20 years left until that point. So that there's lots of different factors that will feed into what you can borrow. Really, really important to know and understand that right from again, I would say. And then alongside that, you've got kind of everything else. So once the house is is ticked off the list or you've come to sit in there, you've got everything else. And the next biggest thing tends to be pensions as well. And that's when I find people really start to get into it and go, okay, these actually are really different, you know, from one to the next. And depending on exactly what type of scheme you've got, there could be totally different rules about when you can access that money or what it all means or what the sort of features are on an ongoing basis and how it pays out. And it's that's why it's so important to distinguish the difference between the two.
Kate Daly 7:01
Because we talked last time, didn't we, about the difference between a pension pound and a house pound. But actually, what I think you're saying here is there's a big difference, even within the asset class called pensions, about what each pension pound is worth. Because if you've got a defined benefit, a final salary scheme, if you are one of the lucky ones that still has one of those, those pounds are a different value to if you're in a defined contribution or you know, an easy, straightforward pension where you're just paying in into a fund. So actually, if you've got a combination of pensions and it might be one of you's got one type, one of you's got the others, or within the within yourself you might have several different types, then how on earth do you go about comparing all of them?
Molly Haylett 7:51
Yeah, it it's it's not uh nowhere near as easy as the numbers on the tin, like we said, you could have a defined benefit um pension, which typically we'll see something like the NHS teachers' pension, though there are still private sector schemes around, and you've got a defined contribution pension. So for that, I tend to say to people, think about like your like your nest or your you know a Viva or something like that, like a standard and more standard scheme. £100,000 is really different, but not only is it worth different amounts, the way that you could access that money and when you can access it could be different as well, which is absolutely worth taking into consideration, particularly if there's an age gap or an income gap between you as well, um, or health, you know, is another one to think about. The way that we normally do this with our clients, um, and you'll know about this, Kate, actually, because the pension and divorce report, which is part of amicable as well, is that we we commission a report so you can get a completely unbiased report, which just takes out all of the emotion from either side and just gives pure numbers and it's it just looks at okay, what's everybody got? It values them appropriately. So an actuary will do the valuation where and that's essentially like a really, really clever specialist that knows exactly what it all means.
Kate Daly 9:02
So is that what's called a fair market value? So instead of just what the valuation is from your pension provider, somebody takes that information, looks through all the information in the pension scheme and works out. So it's kind of like doing algebra, isn't it, where you've got to translate into things that can actually be added together or divided or whatever. Yeah.
Molly Haylett 9:20
Yes, exactly, because there's lots of benefits on a defined benefit scheme that can't be quantified necessarily in that CETV. So they all get taken into account, and then you'll get what we would say, exactly like you said, the fair market value. And it makes it much easier to compare. And then we can turn it into income. So instead of looking at um £100,000 versus £100,000 and somebody saying, by the way, they're different, you can translate it into income and say, Well, actually, this is what it means at 67. That's what your income system will look like at the moment.
Kate Daly 9:51
Right. So if we were married, Molly, and we both had £100,000 in our pension, what it means to me as a slightly older lady might be very different to what it means to you as a younger person and so on and so forth. And it's not just age, is it? There's all sorts of factors that go into it. But just splitting on the numbers, even when you've got your fair market value, doesn't mean you're going to get the same income in retirement. So if you are, if you've got large pensions or you're closer to retirement, it makes a lot more sense by the sounds of it to get a pod report where you can actually have that information and make a decision. And it might not change your decision. You might still want to split in a certain way, but at least you're doing it in the full knowledge of what it actually means to both of you.
Molly Haylett 10:37
Yeah, well, I'm 100%. And all the factors you've mentioned, but then also so many others, even if you've just got slightly different pension schemes, you could have defined benefit schemes. Um, and then you go a layer further and find out that your defined benefit scheme is actually different from my defined benefit scheme. So even as you get into there, they could have completely different sets of rules. And it takes out, I find, is that because you rented with a house, you know, what's better for one might be worse for the other. It takes out all of that emotion and it just gives the unbiased report and the numbers. And actually looking at it in the future, because you're dealing with investments predominantly, so the defined benefit schemes are kind of income-producing vehicles. So they're almost, they pay you a bit like a salary in the future. Whereas standard pensions, defined contribution schemes are a pot of money. And if markets do well, they might get bigger, if markets don't do well, it might get smaller, so it fluctuates a bit more in value as well. Um, but understanding the differences between those two pots, when they're going to pay out, kind of what flexibility you've got with them as well, and what else you've got available overall, which is why state pensions are so important. If one of you's got a full state pension, one of you hasn't, that will get taken into consideration as well. But it just gives you that pure numbers perspective to go, right? Okay, actually, when we are both at 67, which could be completely different, could be years apart from when we're both at that same age, but when we are at that same age, how can we both have the right and fair split of income? And that's what the report tells you, and they're really, really valuable.
Kate Daly 12:08
Brilliant. So it sounds like in this middle stage of the divorce process, then there's a lot more nuance involved. So you've done your first stage, getting your basic information, and now you're looking at some of the more deep dive detail. And it feels like this stage is about really upskilling yourself in knowledge and what you might have missed. This is the bit where it feels like sometimes you don't know what you don't know. You're in danger of making decisions that look fair on the surface, but underneath might be holding hiding a sort of multitude of unfairness. So it feels like this is the point where you really do need somebody to help you and guide you through and get some expert advice on how it's fair to split the house, what how mortgage capacity factors in, what net values look like because they're different to gross values, and what different pensions are available and what the splits can do to your long-term and medium-term future. Brilliant. Thank you. That's a fabulous summary of the middle part of divorce. I'm looking forward to seeing you next time so we can decide and discuss what happens when you've actually done the deed, the divorce is over, and you're staring down the barrel of your new financial reality. So I'll catch up with you later for that conversation. Thanks, Molly. Bye. That's it for part two. Thanks, Molly. Next week we're covering money after your divorce is finalized. Find out how to get familiar with your new cash flow, sort out admin like your wills and pension beneficiaries, and start planning for your new financial reality. And of course, you can find me on LinkedIn and Instagram and hear about new podcast episodes by subscribing for updates and visiting thedivorsepodcast.com or find us on your favourite listening platform. We'd love to know how we can help further, so please share your questions on divorce separation or co parenting with us. They might just be a topic of a future episode.